CHFA Schools to Home for Denver Public Schools Employees
DPS is the largest school employer in Colorado at 190 schools, in the market where its staff are most thoroughly priced out.

Yes, Denver Public Schools employees qualify for CHFA Schools to Home, and it is not limited to teachers. Any full-time employee of the 190 schools on CHFA's eligible-employer list qualifies whatever their job title, and only one borrower on the loan has to be the school employee.
On a $500,000 home that is roughly $100,000 of down payment help against a $400,000 first mortgage, with no monthly payment on the assistance and no mortgage insurance. Household income must be at or below $178,920, the minimum credit score is 620, and there is no purchase price limit and no first-time-buyer requirement. You repay the assistance plus a share of the home's appreciation when you sell or refinance.
Yes, Denver Public Schools employees qualify for CHFA Schools to Home, and it is not limited to teachers. Any full-time employee of the 190 schools on CHFA's eligible-employer list qualifies whatever their job title, and only one borrower on the loan has to be the school employee.
On a $500,000 home that is roughly $100,000 of down payment help against a $400,000 first mortgage, with no monthly payment on the assistance and no mortgage insurance. Household income must be at or below $178,920, the minimum credit score is 620, and there is no purchase price limit and no first-time-buyer requirement. You repay the assistance plus a share of the home's appreciation when you sell or refinance.


with Zach Belloni, Speak Straight Mortgage

Denver Public Schools runs 190 schools, more than any other employer on CHFA's eligible list. It is also the district whose staff have been pushed furthest out of the city they work in.
CHFA Schools to Home covers up to 25% of the first mortgage toward the down payment and eligible closing costs for any full-time DPS employee, with no monthly payment on the assistance. There is no first-time-buyer requirement, so a previous owner who sold and rented for years is still eligible.
All 190 Denver County 1 schools on CHFA's eligible-employer list. Search yours. Working at any of them makes you eligible, whatever your job title is, and only one borrower on the loan has to be the school employee.
Work for a charter, a BOCES, or another Colorado district? The full statewide list is on our Colorado guide.
Every DPS school on CHFA's eligible-employer list
All 190 Denver Public Schools campuses qualify — 138 district-run schools and 52 DPS-authorized charters. Employment at any of them counts, whatever your job title.
District-run schools (138)
- Abraham Lincoln High School
- Academia Ana Marie Sandoval
- Asbury Elementary School
- Ashley Elementary School
- Barney Ford Elementary School
- Barnum Elementary School
- Beach Court Elementary School
- Bear Valley Middle School
- Bradley International School
- Bromwell Elementary School
- Brown International Academy
- Bruce Randolph School
- Bryant Webster Dual Language ECE-8 School
- Career Education Center Early College
- Carson Elementary School
- Centennial A School for Expeditionary Learning
- Center for Talent Development at Greenlee
- Charles M. Schenck (CMS) Community School
- Cheltenham Elementary School
- Cole Arts and Science Academy
- Colfax Elementary School
- College View Elementary School
- Columbine Elementary School
- Compassion Road Academy
- Contemporary Learning Academy
- Cory Elementary School
- Cowell Elementary School
- Creativity Challenge Community
- Delta High School
- Denison Montessori School
- Denver Center for 21st-Century Learning at Wyman
- Denver Center for International Studies
- Denver Center for International Studies at Fairmont
- Denver Green School Northfield
- Denver Green School Southeast
- Denver Montessori Junior/Senior High School
- Denver Online
- Denver School of the Arts
- Dora Moore Elementary
- Doull Elementary School
- Dr. Martin Luther King Jr. Early College
- Eagleton Elementary School
- East High School
- Edison Elementary School
- Ellis Elementary School
- Emily Griffith High School
- Escalante-Biggs Academy
- Excel Academy
- Farrell B. Howell ECE-8 School
- Florence Crittenton High School
- Florida Pitt-Waller ECE-8 School
- Force Elementary School
- Garden Place Academy
- George Washington High School
- Godsman Elementary School
- Goldrick Elementary School
- Grant Beacon Middle School
- Grant Ranch ECE-8 School
- Green Valley Elementary School
- Gust Elementary School
- Hallett Academy
- Hamilton Middle School
- Hill Campus of Arts and Sciences
- Holm Elementary School
- Inspire Elementary
- Isabella Bird Community School
- Joe Shoemaker School
- John F Kennedy High School
- John H. Amesse Elementary
- Johnson Elementary School
- Kaiser Elementary School
- Kepner Beacon Middle School
- Knapp Elementary School
- Kunsmiller Creative Arts Academy
- Lake Middle School
- Legacy Options High School
- Lena Archuleta Elementary School
- Lincoln Elementary School
- Lowry Elementary School
- Manual High School
- Manual Middle School
- Marie L. Greenwood Academy
- Marrama Elementary School
- Maxwell Elementary School
- McAuliffe International School
- McGlone Academy
- McKinley-Thatcher Elementary School
- McMeen Elementary School
- Merrill Middle School
- Montbello Career and Technical High School
- Montbello High School
- Montbello Middle School
- Montclair School of Academics and Enrichment
- Morey Middle School
- Munroe Elementary School
- Newlon Elementary School
- North High School
- North High School Engagement Center
- Northeast Early College
- Northfield High School
- Oakland Elementary
- Palmer Early Childhood Education Center
- Park Hill School
- Pascual Ledoux Academy
- Place Bridge Academy
- Polaris Elementary School
- Prep Academy
- Respect Academy
- Responsive Arts & STEAM Academy FNE
- Robert F. Smith STEAM Academy
- Sabin World School
- Samuels Elementary School
- Sandra Todd-Williams Academy
- Skinner Middle School
- Slavens K-8 School
- Smith Elementary School
- South High School
- Southmoor Elementary School
- Steck Elementary School
- Stedman Elementary School
- Steele Elementary School
- Stephen Knight Center for Early Education
- Summit at Castro
- Swansea Elementary School
- Swigert International School
- Teller Elementary School
- Thomas Jefferson High School
- Traylor Academy
- Trevista at Horace Mann
- University Park Elementary School
- Valdez Elementary School
- Valverde Elementary School
- Vista Academy
- West High School
- Westerly Creek Elementary
- Whittier ECE-8 School
- William (Bill) Roberts K-8 School
- Willow Elementary School
DPS-authorized charter schools (52)
- 5280 High School
- Academy 360
- AUL Denver
- Colorado High School Charter - GES
- Colorado High School Charter - Osage
- Compass Academy
- Denver Justice High School
- Denver Language School
- Downtown Denver Expeditionary School
- DSST: Cedar High School
- DSST: Cedar Middle School
- DSST: Cole High School
- DSST: Cole Middle School
- DSST: College View High School
- DSST: College View Middle School
- DSST: Conservatory Green High School
- DSST: Conservatory Green Middle School
- DSST: Elevate Northeast High School
- DSST: Elevate Northeast Middle School
- DSST: Green Valley Ranch High School
- DSST: Green Valley Ranch Middle School
- DSST: Montview High School
- DSST: Montview Middle School
- French American School of Denver
- Girls Athletic Leadership School Middle School
- Highline Academy Northeast
- Highline Academy Southeast
- KIPP Denver Collegiate High School
- KIPP Northeast Denver Leadership Academy
- KIPP Northeast Denver Middle School
- KIPP Northeast Elementary
- KIPP Sunshine Peak Academy
- KIPP Sunshine Peak Elementary
- Monarch Montessori
- Odyssey School of Denver
- Omar D Blair Charter School
- RiseUp Community School
- Rocky Mountain Prep Berkeley
- Rocky Mountain Prep Creekside
- Rocky Mountain Prep Federal
- Rocky Mountain Prep Green Valley Ranch
- Rocky Mountain Prep Noel
- Rocky Mountain Prep RISE
- Rocky Mountain Prep Ruby Hill
- Rocky Mountain Prep SMART
- Rocky Mountain Prep Southwest
- Rocky Mountain Prep Sunnyside
- Rocky Mountain Prep Westwood
- SOAR at Green Valley Ranch
- University Prep - Arapahoe St.
- University Prep - Steele St.
- Wyatt Academy
How the money actually works
The assistance arrives as a second mortgage with no monthly payment. Nothing is due on it while you live in the house. It comes due when you sell, refinance or pay off the first mortgage, or the home stops being your primary residence.
At that point you repay the assistance plus a share of the home's appreciation, which goes back to Colorado's Public School Permanent Fund. Your share of the gain matches the share of the price the fund put in, so if it covered 20% of the purchase you keep 80% of the growth. If the home has not appreciated, the appreciation piece is zero. We put your own numbers on paper before you sign anything, and the statewide guide walks through a full example.
What Denver Public Schools employees need to qualify
- Household income at or below $178,920
- Credit score of 620 or better
- A Fannie Mae conventional 30-year fixed on a home you will live in
- Single-family, PUD, condo or double-wide manufactured
- No first-time-buyer requirement, so a previous owner is fine
- CHFA homebuyer education plus the program's financial-commitment course
Buying in the city you teach in
A $500,000 Denver house asks $100,000 for the down payment, which is the entire reason so many DPS staff commute in from Aurora, Thornton or further. The program covers that number and drops mortgage insurance off the payment at the same time.
Where a $400,000 first mortgage still lands is the real question, and the answer changes every few months. Condos are worth a specific mention: the loan is a Fannie Mae conventional, so the building itself has to be warrantable, and a building with litigation or thin reserves can kill an otherwise perfect file. We check the project before you write, not after.
Start with the numbers, not an application
Schools to Home runs through CHFA participating lenders and it starts with a short conversation. We confirm your employer is on the list, run your income against the cap, and show you the assistance and the appreciation share side by side at the price you are actually shopping. Nothing is submitted anywhere until you say so.
See your Denver Public Schools numbers →
The Denver loan limit changes what this program can buy
Schools to Home sits behind a Fannie Mae 30-year fixed first mortgage, so the first mortgage has to stay inside the conforming loan limit for the county you buy in — and Denver's is not the same as the rest of the state.
Two practical consequences for a DPS employee. First, the Denver metro counties have a high-balance band from $832,751 to $862,500 that Colorado Springs simply does not have — over the baseline there, a loan is a jumbo with no agency financing behind it. Second, because the assistance is calculated as up to 25% of the first mortgage, a first mortgage at Denver's $862,500 limit pairs with roughly $215,600 of deferred second, which puts a purchase price near $1,078,000 inside the program's reach on paper.
Straight answer on that ceiling: almost no DPS employee will reach it. The program's income cap is $178,920 for the household, and a single educator's salary will not support an $862,500 loan payment long before the loan limit becomes the binding constraint. The limit matters in two real cases — a two-income household where only one person works for the district, and a buyer in Denver proper where the same house costs more than it would in Adams or Jefferson County. For everyone else the honest ceiling is your debt-to-income ratio, not the county's.
The other Denver-metro districts
Each one has its own page, its own school list and its own price ladder.
- Jeffco Public Schools 143 schools
- Adams 12 Five Star Schools 53 schools
Zooming out: the statewide guide covers every eligible Colorado school employer, and there are separate pages for Aurora and Colorado Springs.
Frequently Asked Questions
Can a Denver Public Schools employee use CHFA Schools to Home?
How much down payment help on a $500,000 Denver home?
Can I use it on a Denver condo?
Do I have to buy inside Denver?
What the assistance actually costs you
Schools to Home is not a grant. The state second mortgage is repaid in full when you sell, refinance, pay off the first mortgage, or stop living in the home — and on top of that you repay a fixed share of the appreciation. That share is the original second divided by the original purchase price, and it is locked at closing.
On a $400,000 purchase the first mortgage is $320,000 and the state second is $80,000, so the share is 20%. Sell seven years later at $491,950 and the gain is $91,950 — you repay the $80,000 plus $18,390 of appreciation. Against a conventional 3% down loan, which costs you $12,000 at closing and carries mortgage insurance until year 12, Schools to Home still leaves you roughly $31,652 ahead in that scenario — $12,000 you never put down, $55,014 of lower payments over seven years, less the $35,361 of equity the appreciation share costs you. A home that loses value owes no appreciation share, but the second is still repaid in full.
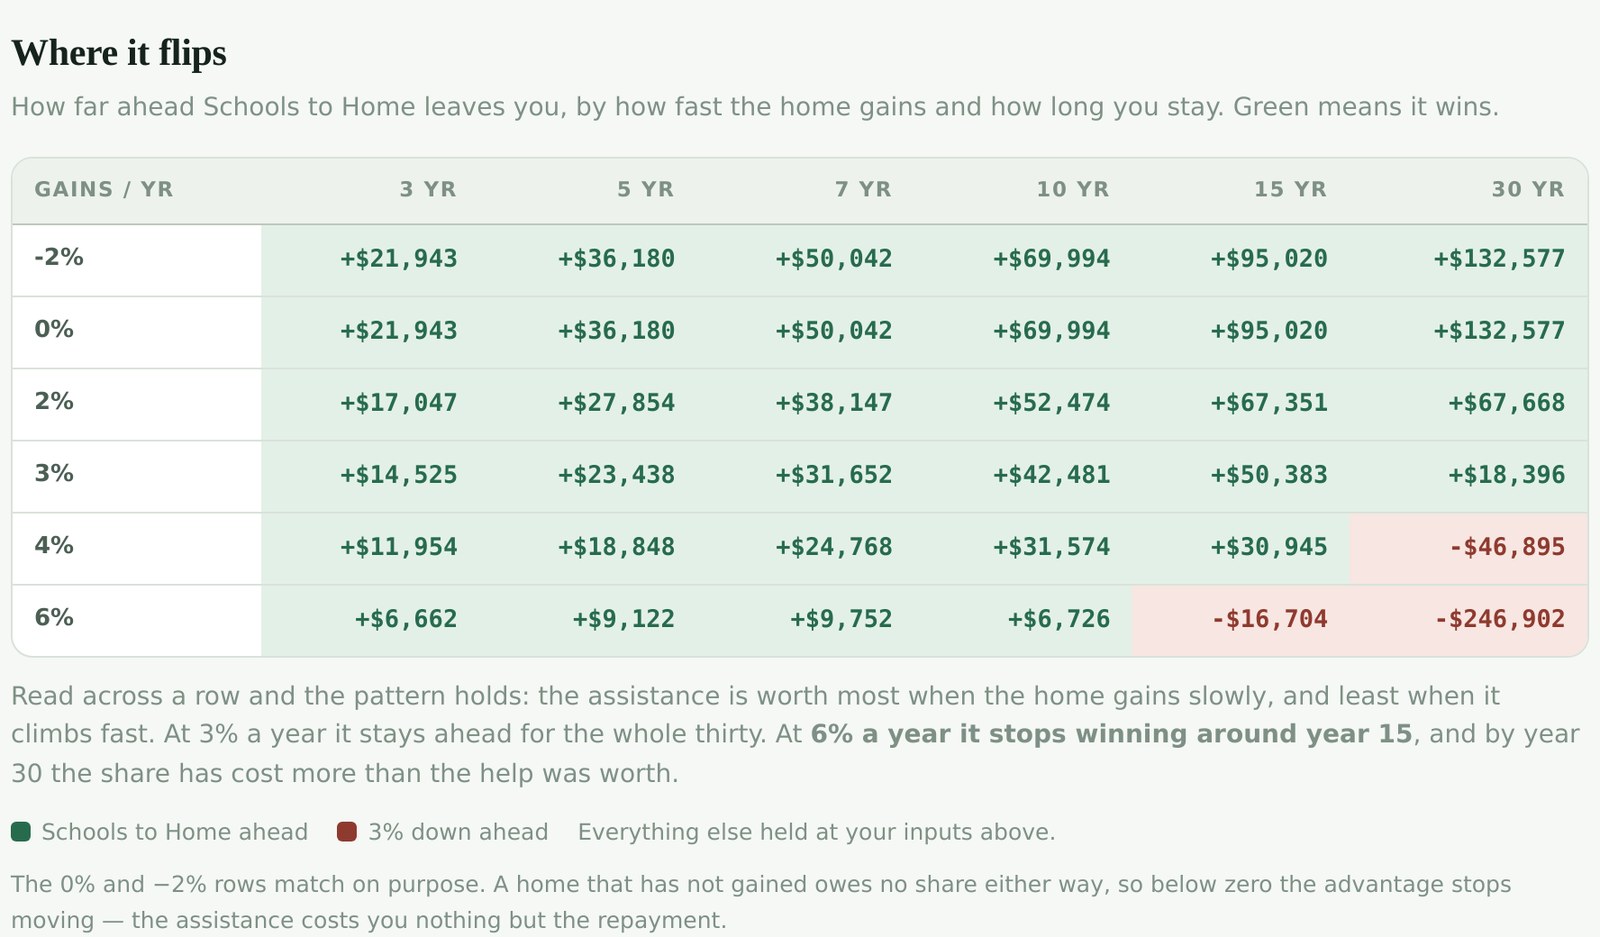
The balance shifts with how fast the home gains and how long you stay. At 3% a year the assistance stays ahead for the full thirty years; at 6% a year it stops winning between years 10 and 15. Put your own price, rate and timeline in below.
What the down payment help really costs you
Colorado pays your down payment and you skip mortgage insurance entirely — in exchange for a fixed slice of every dollar your home gains. Here is the trade, in your numbers.
Your situation
Change anything — everything below updates as you type.
After giving back the assistance and its share of the gain, Schools to Home still leaves you ahead by
Selling in year 7 at 3.0% a year. That counts the $12,000 you keep at closing, $55,014 of lower payments and no mortgage insurance, against $18,390 of appreciation owed on top of the $80,000 you borrowed.
What makes up that number
- Cash you keep at closing
- +$12,000
- Lower payments over 7 years, incl. no PMI
- +$55,014
- Equity given up at sale
- -$35,361
- Schools to Home ahead by
- +$31,652
Your payment starts about $662 a month lower, and you bring $12,000 less to the closing table. Set against that, you hand back $18,390 of appreciation on top of the $80,000 you borrowed, which is why the equity line runs the other way.
Priced at 6.875% on Schools to Home and 6.625% on the 3% down loan — a CHFA bond-funded first mortgage prices above a market conventional loan, which is the trade you make for the assistance — with PMI at 0.50% a year. These are illustrative, not quotes. Change any of them above and every figure on this page moves with it.
Schools to Home Ahead
80% first mortgage, no mortgage insurance, state second covers the rest.
- Cash at closing
- $0
- Monthly payment
- $2,399
- Mortgage insurance
- none
- Your appreciation share
- Equity when you sell
- $103,629
Conventional 3% down Behind
You fund the down payment and carry PMI until you reach 80%.
- Cash at closing
- $12,000
- Monthly payment
- $3,061
- PMI, drops off
- $162/mo, gone year 12
- Your appreciation share
- none — you keep it all
- Equity when you sell
- $138,990
Where it flips
How far ahead Schools to Home leaves you, by how fast the home gains and how long you stay. Green means it wins.
Read across a row and the pattern holds: the assistance is worth most when the home gains slowly, and least when it climbs fast. At 3% a year it stays ahead for the whole thirty. At 6% a year it stops winning around year 15, and by year 30 the share has cost more than the help was worth.
The 0% and −2% rows match on purpose. A home that has not gained owes no share either way, so below zero the advantage stops moving — the assistance costs you nothing but the repayment.
How the share is figured
CHFA sets your share once, at closing, and it never changes.
- You buy at $400,000. The first mortgage is 80% of that, $320,000 — the reason there is no mortgage insurance.
- The state second is $80,000. That is 25.0% of the first mortgage, and 20.0% of the purchase price.
- Your share is that second divided by the price: 20.0%. It is locked at closing and never moves.
- Sell in year 7 for $491,950 and the gain is $91,950.
- You owe the $80,000 back, plus 20.0% of that gain — $18,390. Total $98,390.
- Nothing is due until you sell, refinance, pay off the first, or stop living there.
What this assumes
- The first mortgage is 80% of the purchase price, which is what keeps mortgage insurance off the loan. The state second covers up to 25% of that first mortgage — 20% of the price. Take less and you bring the difference in cash.
- Your appreciation share is the original second divided by the original purchase price, applied to the gain between your purchase price and your sale price. A home that loses value owes no share, but the second is still repaid in full.
- Both loans are 30-year fixed and amortized properly, so the payoff figures sit slightly below CHFA's own illustration, which uses the opening balance.
- PMI on the 3%-down loan is removed once the balance amortizes down to 80% of the purchase price. That is the automatic rule. If the home climbs quickly you could cancel earlier by paying for an appraisal, which would narrow the gap — so this assumption leans slightly in Schools to Home’s favor.
- Taxes, insurance and HOA are identical in both columns, so they change the payment but never the comparison.
- Rates and mortgage insurance are assumptions, not quotes: 6.875% on the Schools to Home first mortgage, 6.625% on the conventional 3% down loan, and PMI at 0.50% of the loan balance per year. A 97% loan-to-value loan carries pricing adjustments an 80% loan does not, which is why the two rates differ. Your own quote depends on credit score, loan amount, property and the day you lock.
- Cash you keep at closing and each month of payment difference are counted at face value — no investment return, no tax effects.
- Selling costs are left out. They are the same either way.
Estimate only, not a commitment to lend or a quote. Rates, mortgage insurance and program terms change. CHFA sets Schools to Home terms — including income limits, a 620 minimum credit score, full-time employment at an eligible Colorado public school employer, and two required education courses — and verifies eligibility at application. Speak Straight Mortgage · Company NMLS 2426226 · Equal Housing Opportunity.
Prefer it on its own page? Open the Schools to Home estimator.
Keep reading
See if your school qualifies
Answer a few quick questions about your situation — no hard credit pull, no pressure. We'll confirm your eligibility for CHFA Schools to Home and map out your options.
Check my eligibility